How to Use the LoanFunders Fix & Flip Calculator: A Step-by-Step Guide With Real Deal Examples
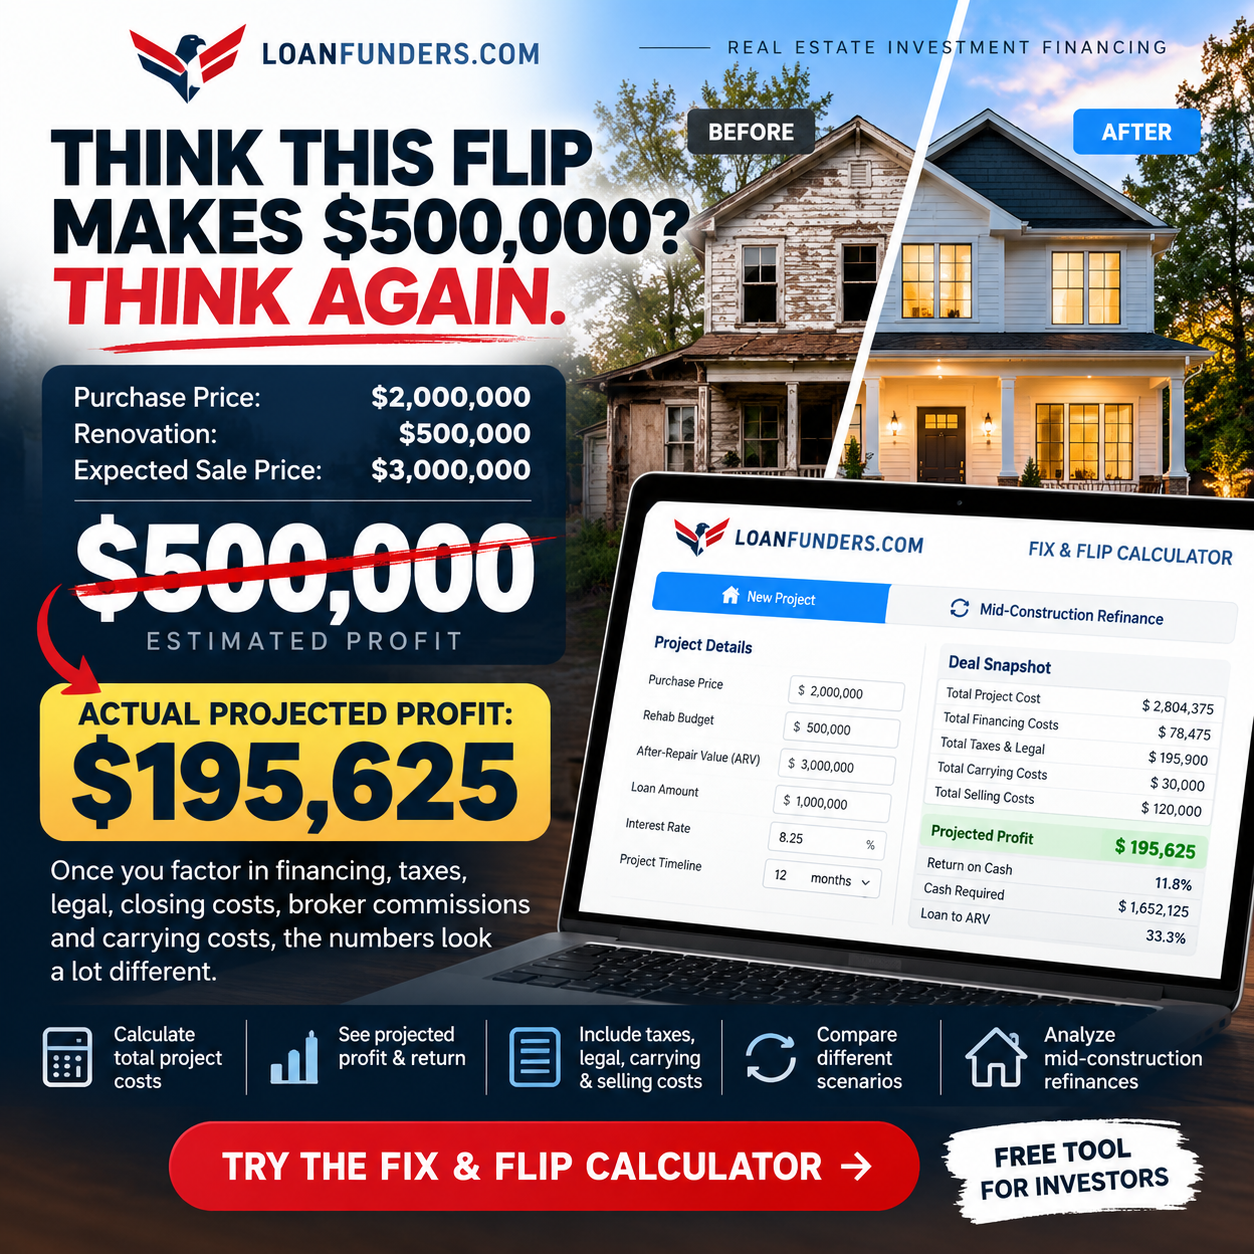

In our last post, we introduced the new LoanFunders Fix & Flip Calculator, a free tool designed to help real estate investors estimate their true project costs, cash required, projected profit and return on cash.
Now let’s actually put it to work.
https://loanfunders.com/fix-flip-calculator/
One of the biggest mistakes a real estate investor can make is looking at a potential flip like this:
Purchase Price + Renovation Cost = Total Investment
Then:
After-Repair Value – Total Investment = Profit
If only it were that simple.
Real fix & flip projects have financing costs, origination points, property taxes, title insurance, mortgage recording taxes, legal expenses, broker commissions, transfer taxes, appraisal fees, filing fees and other carrying costs.
Leave enough of those out and a deal that looks fantastic on paper can become a very average deal—or even a losing one.
That’s exactly why we built the LoanFunders Fix & Flip Calculator.
Let’s walk through both sides of the calculator using real-world examples:
You can follow along with your own deal using our free calculator here:
https://loanfunders.com/fix-flip-calculator/
Let’s start with a hypothetical New York investment property.
We’re considering purchasing a property for $2,000,000. We believe it will be worth $3,000,000 after renovation, and we expect to spend $500,000 completing the project.
Sounds pretty good at first glance, right?
Buy for $2 million, put in $500,000 and sell for $3 million.
That’s a $500,000 spread.
But is that a $500,000 profit?
Not even close.
Let’s run the numbers.
This is straightforward. Enter the amount you’re paying to acquire the property.
For our example:
Purchase Price: $2,000,000
This becomes the starting point for the entire analysis.
The After-Repair Value, commonly called ARV, is the estimated value of the property once your renovation is complete.
If you’re planning to sell the property after the rehab, this is essentially your expected sale price.
For this example:
ARV: $3,000,000
One important point: be realistic.
A calculator is only as useful as the numbers you put into it. Don’t use the number you hope the property will sell for. Use an ARV supported by realistic comparable sales and current market conditions.
Next, enter the amount you expect to borrow.
For our example:
Loan Amount: $1,000,000
The calculator uses the loan amount to help determine financing costs, leverage and the amount of your own cash required in the transaction.
Enter the remaining work required to complete the renovation.
In our example:
Renovation Budget: $500,000
Again, conservative numbers matter.
If your contractor says the job will cost $450,000 but you believe change orders and unexpected expenses could push it to $500,000, we’d rather analyze the deal using $500,000.
It’s better to discover that a deal doesn’t work before you buy it than after you’ve started opening walls.
Now we tell the calculator how we’re financing the project.
How long do you realistically expect to own the property before selling it?
Our example assumes:
12 months
This number matters because time costs money.
Every additional month can mean additional interest, taxes, insurance, utilities, maintenance and other carrying costs.
A project that produces a strong return in six months may produce a very different return if it takes 18 months.
For our hypothetical example, we’ll use:
Interest Rate: 8.25%
This allows you to see what the deal looks like using your expected financing cost.
Don’t manipulate the rate just to make the project look better. The purpose of the calculator is to determine whether the investment works under realistic financing assumptions.
Our example assumes:
1 origination point
On a $1,000,000 loan, one point represents $10,000.
Points are part of the cost of financing and should absolutely be included when determining the real profitability of the project.
This field is particularly important.
The calculator gives you the ability to distinguish between paying interest on the full principal balance and paying interest based on funded draws.
In our example, we select:
No—as drawn
Why does this matter?
On many rehab and construction loans, funds may be advanced as work progresses. If you’re only paying interest on money that has actually been funded, your interest expense can be different from a structure where interest is charged on the entire commitment from day one.
This seemingly small detail can have a meaningful effect on the economics of a project.
This is where many back-of-the-napkin flip calculations start falling apart.
Real estate transactions have expenses on both the purchase and sale.
Our calculator allows you to include them.
For our example, we enter:
2% of the loan amount
The calculator applies that assumption to the financing.
Actual mortgage recording taxes vary by location and transaction, so use the percentage appropriate for your deal.
Our example assumes:
1% of the purchase price
Again, your actual cost may vary, but the important thing is that we’re accounting for it rather than pretending it doesn’t exist.
Selling a property can create its own taxes and transaction expenses.
Our example assumes:
1% of the sale price
On a $3 million sale, percentages become real money very quickly.
The calculator also provides a field for a potential mansion tax at sale.
For this particular example, we’ve entered:
0%
If a tax applies to your particular property, location or transaction, enter the appropriate percentage.
We assume:
4% broker commission
On a $3 million sale, that’s $120,000.
That’s exactly the type of expense that can be forgotten when someone casually says:
“I bought it for $2 million, put $500,000 into it and sold it for $3 million, so I made $500,000.”
No—you didn’t.
We’re starting to see why.
Our example assumes annual property taxes and maintenance equal to:
1% of ARV per year
With a $3 million ARV and a 12-month project, the calculator estimates:
$30,000
This is another reason your timeline matters.
The longer you hold the property, the more carrying costs can eat into your profit.
Click Fixed Closing Costs and you’ll find several additional expenses that can be customized for your particular transaction.
Our example includes:
These may look small compared with a multimillion-dollar project.
But that’s the point.
Real profitability isn’t calculated by ignoring the smaller expenses.
It’s calculated by adding all of them together.
This is where the calculator becomes really useful.
As you enter or change your assumptions on the left side, the results on the right show you what those assumptions could mean for your investment.
For our $2 million example, here’s what happens.
Remember our original napkin calculation?
$3,000,000 ARV
minus $2,000,000 purchase
minus $500,000 renovation
That looked like:
But after accounting for financing, carrying costs, taxes, title, legal expenses, commissions and the other costs associated with buying, holding and selling the property, our calculator estimates:
That’s a difference of more than $300,000 from the simplistic calculation.
That’s why running the complete numbers matters.
The Deal Snapshot breaks the project down into its major components.
For this example:
Sale Price: $3,000,000
Purchase Price: $2,000,000
Renovation: $500,000
Interest & Origination Points: $78,475
Property Tax & Maintenance: $30,000
Taxes, Title, Legal & Other: $195,900
Subtract that from the projected $3,000,000 sale price and you get:
Now we’re analyzing a real investment—not just a purchase price and ARV.
The calculator estimates a:
Return on cash is important because profit alone doesn’t tell you how efficiently your capital is working.
Making $100,000 after investing $300,000 of your own money is very different from making $100,000 after tying up $1.5 million.
In our example, the calculator estimates:
Borrower Cash in Deal at Closing: $1,553,650
and:
Cash in Deal After 12 Months: $1,652,125
Based on the projected $195,625 profit, that produces an estimated:
Now an investor can compare this opportunity against another flip, another property, another investment strategy—or simply decide whether the projected return adequately compensates them for the risk and work involved.
Our example shows:
Loan-to-ARV compares the loan amount with the property’s projected value after renovation.
In this case:
$1,000,000 Loan ÷ $3,000,000 ARV = 33.3%
This gives you a quick look at the leverage in the deal relative to its expected completed value.
Now let’s look at one of our favorite features.
Not every investor finds us before buying the property.
Sometimes we get the call halfway through the project.
Maybe your existing loan is maturing.
Maybe your current lender isn’t funding draws quickly enough.
Maybe construction went over budget.
Maybe you originally purchased with cash or another short-term financing source.
Or maybe you simply need a new loan to finish the project.
That’s why we created the Mid-Construction Refinance tab.
Instead of pretending you’re purchasing the property today, this section lets you analyze a project that’s already underway.
Most of the fields work exactly as they do in the Purchase calculator, but there are several important additions.
Enter the amount required to pay off your current lender.
For example, suppose our investor owes:
$1,000,000
This matters because a mid-construction refinance isn’t starting with a clean slate. The new financing may need to retire existing debt before additional capital can be used elsewhere in the project.
Next, enter the amount of capital improvements already completed.
Let’s say our investor has already completed:
$200,000 of the renovation
This helps distinguish between money already invested into the property and the renovation work that still remains.
If the original renovation budget was $500,000 and you’ve already completed $200,000 of the work, you might have approximately:
$300,000 remaining
Your actual numbers will depend on the project.
Enter the date you originally purchased the property.
Why include this?
Because a mid-construction refinance needs to recognize that the project didn’t begin today. You’ve already owned the property for a period of time and may already have capital invested in the deal.
The original closing date gives the calculator context for the project’s timeline.
On a mid-construction refinance, pay close attention to this field.
This should reflect the remaining work to complete, not blindly repeat your original construction budget.
If you started with a $500,000 rehab and $200,000 of work has already been completed, don’t tell the calculator you still need $500,000 unless you actually do.
The goal is to analyze the project as it exists today.
Once you’ve entered the existing loan payoff, completed CapEx, remaining renovation budget, proposed loan amount, financing terms, taxes and expenses, the right side again gives you the key metrics you need to evaluate the project.
You’ll see:
The Cash Position section then helps you understand how much of your own capital is tied up in the project and what your projected return on that capital could be.
That’s extremely valuable when you’re trying to answer a question we hear all the time:
Instead of guessing, run the numbers.
Here’s where we’d encourage investors to go beyond simply entering one set of numbers.
Once you’ve entered your deal, start changing the assumptions.
What happens if your $3 million ARV becomes $2.85 million?
What if your $500,000 renovation becomes $575,000?
What if the project takes 15 months instead of 12?
What if your broker commission is higher?
What if financing costs change?
Does the deal still work?
This is what we mean by stress-testing a real estate investment.
The goal isn’t to make the calculator produce a number you like.
That’s a much more useful question.
Interest rates are high right now. There’s no reason to pretend otherwise.
But investors are still finding excellent opportunities.
A higher interest rate doesn’t automatically make a bad deal—and a low interest rate never automatically made a good one.
Purchase price matters.
ARV matters.
Construction cost matters.
Timeline matters.
Leverage matters.
Selling costs matter.
And your margin matters.
In today’s market, less competition can sometimes create opportunities to negotiate better acquisition prices. Motivated sellers still exist. Distressed properties still need buyers. Properties still need renovation. New housing still needs to be built.
The investors succeeding in this environment aren’t ignoring financing costs.
They’re accounting for them and finding deals that still work.
That’s exactly what this calculator is designed to help you do.
Before you make your next offer, take a few minutes and run the entire project.
Not just purchase price.
Not just rehab.
Not just ARV.
Everything.
Use the free LoanFunders Fix & Flip Calculator to estimate your financing costs, taxes, carrying costs, closing expenses, cash required, projected profit and return on cash.
And if you’re already halfway through a project, switch over to the Mid-Construction Refinance tab and see what your numbers look like today.
https://loanfunders.com/fix-flip-calculator/
And if you’ve run the numbers and need financing, send us the deal.
LoanFunders provides financing for Fix & Flip, Ground-Up Construction, Bridge, DSCR and other real estate investment opportunities.
📞 718-635-2377
✉️ george@loanfunders.com
Run the numbers first. Then make the deal.
Calculator results are estimates only. Actual costs, taxes, fees, financing expenses and returns will vary based on property location, lender program, loan structure, project timeline, closing date and other factors. Calculator results are not financial, legal, tax or investment advice and do not constitute a commitment to lend. Business-purpose loans only. All financing is subject to underwriting and approval.